Broker Check


Investment Management Services

Disciplined portfolio management for families and business owners across Greater Boston. We build your allocation around your goals and risk tolerance, keep it on course through every market, and manage it with an eye on costs and taxes.

A conversation about your portfolio, with no obligation to move forward.


  • CFP®, ChFC®, CLU®, TPCP®, and RICP® Credentials on Our Team
  • Advisory Services Through LPL Enterprise, Member FINRA/SIPC
  • Offices in Massachusetts, Rhode Island and Connecticut
  • Serving  Easton, Greater Boston Area, and New England

Investment Management That Adapts to Your Changing Needs

Investment management is the part of your plan that keeps working after the plan is written. It is the ongoing job of building a portfolio that fits your goals, putting the right money in the right accounts, and then watching it closely enough to act when markets, tax rules, or your own circumstances change. It is a different discipline from writing a one-time plan, and it is where many portfolios quietly drift off course.

We manage portfolios for families and business owners in Easton, Sharon, Canton, Walpole, Westwood, and across Greater Boston. Our work covers how your money is invested and how it is maintained: the mix of stocks, bonds, and other assets, where each holding sits for tax purposes, when to rebalance, and how the portfolio connects to your broader plan. For the full picture, this service sits alongside our comprehensive financial planning in Easton.

The result is a portfolio you understand and a process you can see. We explain what you own and why, review it with you on a regular schedule, and adjust it as your needs and the rules around investing evolve. If you want more clarity on how your current portfolio is built, the first step is a conversation.


Why This Matters

How a portfolio is invested and maintained drives more than returns. It drives the tax you owe, the risk you carry, and how much of each dollar stays yours. These are the realities that shape most of the investment conversations we have.

  • 3.8%

    The Net Investment Income Tax

    A 3.8 percent tax applies to net investment income once modified adjusted gross income passes $200,000 for single filers or $250,000 for joint filers. The thresholds are not indexed for inflation, so more households cross them over time, which makes asset location and tax-aware selling part of the job.

    Internal Revenue Service, Topic No. 559
  • 0, 15, 20%

    Long-Term Capital Gains Rates

    Assets held longer than one year are taxed at preferential long-term rates of 0, 15, or 20 percent, while assets sold within a year are taxed as ordinary income. Holding periods and the timing of a sale can change the tax on the same gain, so they factor into every rebalancing decision.

    Internal Revenue Service, Topic No. 409
  • Risk Alignment

    A portfolio should be designed for two different things: your risk tolerance, how much market volatility you are comfortable living with, and your risk capacity, how much risk your plan can absorb without putting your goals in jeopardy. We align the allocation to both, so the portfolio is neither more aggressive than you can stand nor more conservative than your goals need.

  • Asset Location

    The same investment can be taxed very differently depending on which account holds it. Asset location is the practice of placing holdings across your taxable, tax-deferred, and tax-free accounts so the most heavily taxed assets sit in the most sheltered places. Done consistently, it can improve what you keep without changing your overall allocation.

Figures reflect the 2026 tax year and are provided for general information. They are not tax or legal advice. Please consult a qualified tax or legal professional about your own situation.


Our Services

Managing a portfolio is not one task. It is a set of decisions that interact with each other, which is why we coordinate them rather than handling them one at a time.

  • Portfolio Construction and Asset Allocation

    We build your mix of stocks, bonds, potentially alternative investment, and other assets around your goals, time horizon, and tolerance for risk, then document why the portfolio is put together the way it is so the reasoning is clear from the start.

  • Ongoing Oversight and Rebalancing

    Markets move your allocation away from its targets over time. We monitor the portfolio and rebalance on a disciplined basis, so your risk level stays where you intended rather than drifting with whatever rose last.

  • Risk Management and Diversification

    We spread risk across asset classes and sectors and stress-test the plan against down markets, so the portfolio is built to weather volatility rather than react to it. Diversification does not assure a profit or protect against loss.

  • Tax-Aware and Asset-Location Investing

    Where a holding sits matters as much as what it is. We place assets across taxable, tax-deferred, and tax-free accounts with an eye on the taxes they generate, and coordinate with your tax-efficient investing plan.

  • Retirement Portfolio Alignment

    A portfolio built to accumulate rarely suits a household that is now drawing from it. We align the allocation with your retirement income planning, so the investments and the withdrawals work together.

  • Wealth Transfer and Beneficiary Coordination

    Investments pass to the next generation through titling and beneficiary designations, not a will alone. We coordinate those details with your broader financial plan, your attorney, and your CPA.


Why Families Choose to Work with Us

Handing your portfolio to someone is a decision about trust. Ours comes down to three things: planners who have managed money through several market cycles, a team deep enough that your portfolio never rests on one person, and advice given as guidance rather than a sales pitch.

Our Easton office on Norfolk Avenue anchors four locations across Massachusetts, Rhode Island, and Connecticut, so you can meet in person or work with us remotely.

  • Advisory Services Through a Registered Investment Advisor

    Securities and investment advisory services are offered through LPL Enterprise (LPLE), a Registered Investment Advisor, Member FINRA/SIPC, and an affiliate of LPL Financial. When our planners provide investment advice in that capacity, those recommendations are subject to a fiduciary standard of care.

  • Credentialed Planners Across the Team

    CFP®, ChFC®, CLU®, RICP®, and TPCP® designations across the team bring depth in investment, tax, and retirement planning. RICP® conferred by The American College.

  • A Multigenerational Planning Team

    Two families and three generations of planners work side by side, which means continuity of relationship and no single point of failure in how your portfolio is managed.

  • A Disciplined, Cost-Aware Approach

    We build portfolios around your goals and risk tolerance, keep an eye on costs and taxes, and explain the trade-offs in plain terms. Coordination with your CPA and estate attorney is part of the work, not an add-on.
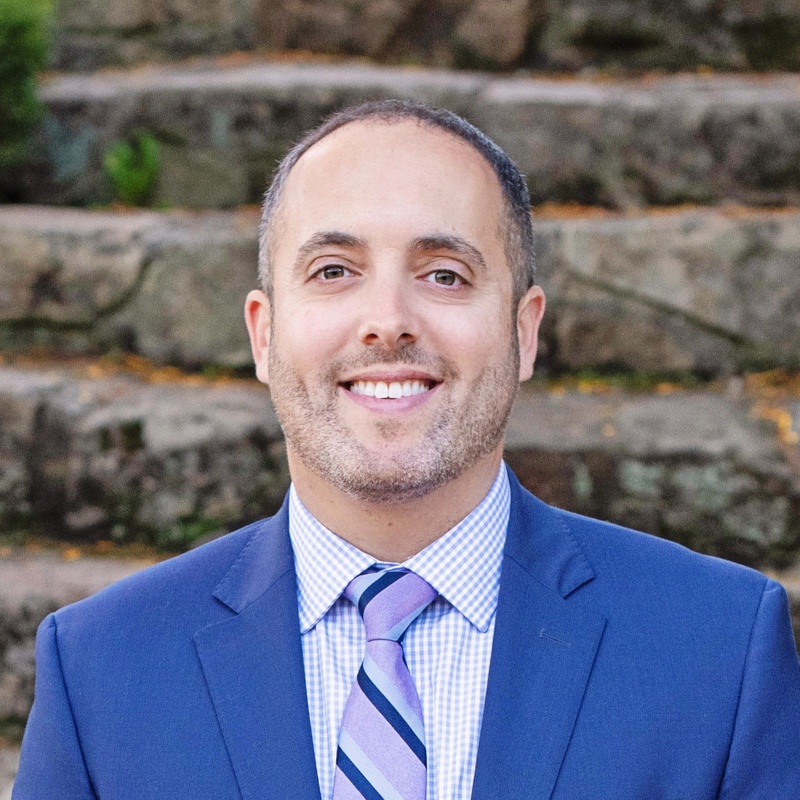
Jordan L. Cohne, RICP, TPCP

Jordan L. Cohne, RICP®, TPCP®

Founder, Managing Partner, Financial Planner

A financial planner since 2004 who began his career alongside his father, Marty, an advisor for 45 years. He holds the Retirement Income Certified Professional® designation and takes a consultative approach centered on education and guidance.
Glenn A. Levine, CLU, ChFC, CFP

Glenn A. Levine, CLU®, ChFC®, CFP®

Managing Partner, Financial Planner

A CERTIFIED FINANCIAL PLANNER™ professional who joined Prudential in 1980 after graduating from Brandeis University. He brings decades of business planning experience and a deep grounding in employee benefits and insurance.
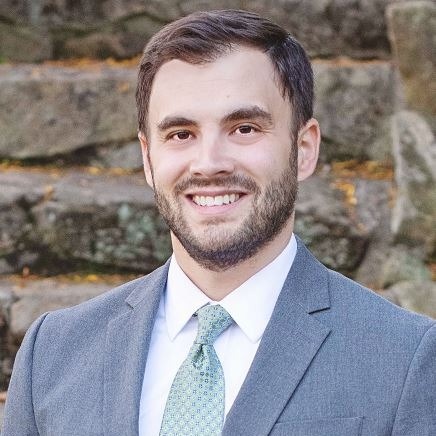
Avi Z. Levine, CFP

Avi Z. Levine, CFP®

Senior Partner, Financial Planner

A CERTIFIED FINANCIAL PLANNER™ professional who began advising in 2016, following his father Glenn into the profession. He focuses on comprehensive planning for clients at every stage, from early accumulation through retirement.
Sophia Pasquariello

Sophia Pasquariello

Associate, Financial Planner

An associate financial planner who moved into advising from a client service role. She researches planning strategies for the households the team serves and starts every relationship by learning the client's own story.
Ashlyn Kelly

Ashlyn Kelly

Associate, Financial Planner

An associate financial planner who holds a Bachelor of Science in Business Administration from Nichols College. She works on both the technical and the relationship sides of planning, helping clients pursue clarity and long-term independence.


Areas We Serve

Our office sits on Norfolk Avenue in Easton, MA, minutes from Route 24 and Route 495. We meet clients in person here and manage portfolios remotely for households across Greater Boston, the South Shore, and southeastern Massachusetts.

Massachusetts Communities

  • Easton
  • Mansfield
  • Foxboro
  • Norton
  • Walpole
  • Canton
  • Sharon
  • Westwood
  • Bridgewater
  • West Bridgewater
  • Raynham
  • Boston

Additional Offices

Southborough, MA · Warwick, RI · Southport, CT

Clarity Wealth Advisors

14 Norfolk Ave, Suite 2
South Easton, MA 02375

508-219-0301

Monday through Thursday, 9:00 AM to 5:00 PM. Friday, 9:00 AM to 2:00 PM.

Schedule a Strategy Session


Schedule an Investment Management Strategy Session 

Whether you are building a portfolio, reviewing one you already hold, or preparing to draw income from it, a conversation gives you clarity on how your money is invested and what it is costing you. We will talk through your goals, your risk tolerance, and how your current allocation measures up.

This is a no-obligation conversation.

Frequently Asked Questions

What Does an Investment Manager in South Easton, MA Do?

An investment manager builds and maintains the portfolio behind your financial plan. That means setting an asset allocation that fits your goals and risk tolerance, choosing where each holding sits for tax purposes, rebalancing as markets move, and reviewing the portfolio with you on a regular schedule. The aim is a portfolio that stays aligned with your plan rather than drifting with whatever the market did last.

What Is the Difference Between Investment Management and Financial Planning?

Financial planning is the broader blueprint: your goals, cash flow, retirement timeline, tax picture, and estate wishes. Investment management is the ongoing work of putting the investable part of that plan to work and keeping it on course. A plan tells you how much to invest and why; investment management decides how the money is allocated, maintains that allocation, and adjusts it as conditions change. The two work best together.

How Often Should an Investment Portfolio Be Rebalanced?

There is no single right interval. Many portfolios are reviewed on a set schedule, such as quarterly or annually, and rebalanced when an asset class drifts beyond a chosen tolerance band rather than on the calendar alone. Rebalancing in a taxable account also has to weigh the capital gains it creates, so the decision is part discipline and part tax awareness. We monitor your allocation and act when the drift, not the date, calls for it.

How Do Taxes Affect My Investment Returns?

Taxes shape what you keep. Assets held longer than one year are taxed at preferential long-term capital gains rates of 0, 15, or 20 percent, while assets sold within a year are taxed as ordinary income, according to the IRS. Where a holding sits also matters: the same fund can generate very different tax bills in a taxable account versus a tax-deferred or tax-free one. We manage holding periods and asset location so more of the return stays with you.

What Is the Net Investment Income Tax?

The Net Investment Income Tax is an additional 3.8 percent tax on net investment income for higher-income taxpayers. It applies once modified adjusted gross income passes $200,000 for single filers or $250,000 for joint filers, and those thresholds are not indexed for inflation, so more households reach them over time. Because a large gain or distribution can trigger it, we model the tax effect of portfolio moves before making them. Source: IRS Topic No. 559.

How Do You Manage Investment Risk?

We start by defining how much risk your goals require and how much you are comfortable taking, then build a diversified allocation across asset classes and sectors to match. We stress-test the portfolio against down markets and rebalance so its risk level stays where you intended. Diversification and asset allocation do not assure a profit or protect against loss in a declining market, but a disciplined structure helps you stay invested through volatility.

Do You Work with Clients Outside of South Easton, MA?

Yes. Our South Easton office serves clients throughout Greater Boston and southeastern Massachusetts, including Easton, Mansfield, Foxboro, Norton, Walpole, Canton, Sharon, Westwood, Bridgewater, West Bridgewater, Raynham, and Boston. We also maintain offices in Southborough, Massachusetts, Warwick, Rhode Island, and Southport, Connecticut, and we work with many clients entirely by video and phone.

How Do I Get Started with Investment Management?

Start with a strategy session. It is a conversation, by phone, video, or in person at our Easton office, in which we learn what you are working toward and you see how we manage money. If it looks like a fit on both sides, the next step is a review of your current holdings, accounts, and goals. You can schedule a session using the button on this page or by calling 508-219-0301. There is no obligation to move forward.